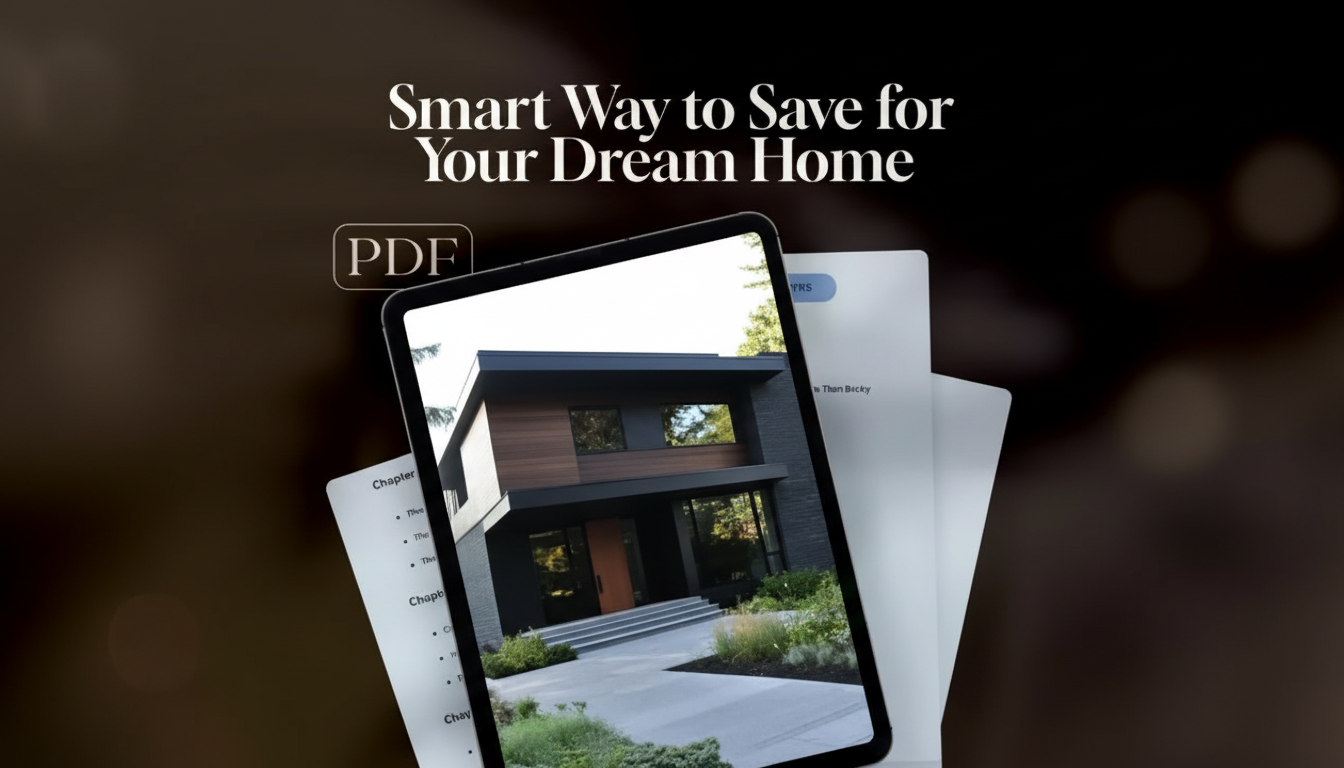
Saving to build a home can feel overwhelming when land, materials, permits, and surprise costs all hit at once. A smart plan breaks a big goal into monthly steps, maps out when cash is needed (not just how much), and reduces the costly “we didn’t know that was due yet” moments that stall builds. Below is a practical way to approach saving so your project stays financially realistic from day one through move-in.
Many first-time builders budget for “construction cost” and still come up short because the total project cost includes far more than materials and labor. A stronger plan separates hard construction from the full list of cash needs—and tracks the timing of each.
| Category | What it can include | Savings move that helps |
|---|---|---|
| Land & closing | Down payment, closing costs, title, survey | Create a dedicated “land fund” with a target date and automatic transfers |
| Design & permits | Plans, engineering, permits, impact fees | Set a pre-build buffer so paperwork costs don’t drain construction cash |
| Site work | Clearing, grading, septic/well, driveway | Get early estimates and save to the high end; site surprises are common |
| Materials & labor | Framing, roofing, MEP, drywall, finishes | Track price volatility and build a contingency for increases |
| Utilities & final steps | Hookups, inspections, landscaping, punch list | Reserve end-phase cash so the home can reach completion without delays |
| Contingency | Change orders, delays, unexpected repairs | Aim for a defined reserve that stays untouched unless truly necessary |
A realistic target starts with a conservative total, then adds buffers for the parts that tend to move: site conditions, material pricing, and timeline shifts.
For broader homebuying and financing education, these resources can help you frame the big picture: Consumer Financial Protection Bureau (CFPB), HUD, and Freddie Mac.
Consistency beats intensity. A plan that works for three months and collapses isn’t a plan—it’s a reset. Make it automatic, simple, and easy to adjust.
The goal isn’t to build “cheap.” It’s to spend on what’s difficult to change later and stay flexible on what can be upgraded over time.
If you want a structured way to turn “dream home” into a repeatable savings system, Brick by Brick: The Smart Way to Save for Your Dream Home (Digital Guide eBook) is designed to keep the process clear and measurable.
If you also like simple, self-paced digital reads for other life goals, browse additional downloads such as Top 10 Must-See U.S. National Parks + Fast Facts (Digital Travel Guide eBook)—an easy way to plan a reward trip once your savings routine is running smoothly.
The right amount depends on your land situation, local costs, and loan type, but most builds require meaningful pre-build cash for plans, permits, testing, and early site work—plus a contingency reserve. Milestone-based targets (pre-build, breaking ground, and finish-to-move-in) are usually more reliable than chasing a single number.
Building costs typically mean hard construction (materials and labor), while total project costs also include land, design, permits/fees, site work, utilities, and end-phase items. People underestimate totals because many expenses show up early or late, outside the main construction contract.
Use line-item ranges instead of single guesses, keep a defined contingency, and prioritize essentials so upgrades don’t crowd out must-haves. Reduce change orders by making key finish selections early and doing periodic check-ins as bids and timelines evolve.



Leave a comment